Sherman Oaks, California
Investment and asset management for real estate owners
KILTY, LLC is a real estate management and investment firm based in Sherman Oaks, California. This is the financial side of owning property: what it earns, what it costs, what it is worth, and what the debt against it requires.
No projections dressed up as certainties
We work with owners and investors across Los Angeles County who want a clear read on their position. That means starting from the rent roll and the expense history you actually have, showing the arithmetic, and naming the parts that depend on decisions nobody has made yet. If a figure rests on an assumption, the assumption gets written down next to it.
Asset management work runs through the whole holding period, not just at acquisition. A property is reviewed while you own it: how income is tracking against plan, where expenses drifted, what the debt calendar looks like, and whether the current plan still fits the building.
Where an asset review starts
- Trailing income and actual operating expenses, month by month.
- Loan terms, maturity date, and what a reset payment looks like.
- Capital items coming due, and how they were last funded.
- Comparable rents and sale activity in the submarket.
Start with net operating income
Net operating income is what the property earns before debt service. Cap rate, debt coverage, and valuation all reference it.
Getting NOI right means using actual income and actual expenses, not a stabilized pro forma that assumes full occupancy at market rent. Vacancy loss belongs in the number. So does the real cost of turning a unit, the management fee, insurance, taxes, and the repairs that recur every year rather than the ones you hope not to repeat.
Most disagreements about a property's value trace back to NOI. An owner using last year's numbers, a lender using a trailing twelve-month figure, and a buyer using a forward projection will land in three different places. That gap is not a rounding error; it is the negotiation. We reconcile the versions explicitly, line by line, so the conversation about price starts from the same page.
Three ways the same building gets valued
Owner's view — last full year, actuals
Reflects the building as operated, including any deferred work.
Lender's view — trailing twelve months
Smooths a single good or bad quarter into the debt test.
Buyer's view — forward projection
Priced on what the buyer intends to run, not what you ran.
Corridor and stairwell, multifamily walk-up — the building's operating reality sits behind every income figure
Cap rate, and what it does and doesn't tell you
Cap rate is NOI divided by price. It tells you what the market is paying for income at a moment in time. It does not tell you whether the building is well run, whether the roof is five years old, or whether the rent roll is sustainable.
Two properties with the same cap rate can carry very different risk. A stabilized apartment building and a mixed-use property with a large vacancy are not comparable just because the math lands nearby. The mixed-use building may be priced for income that has not shown up yet, and the stabilized one may be priced on rents that have already peaked for that block. We use cap rate as one input among several, not as a verdict.
What cap rate is good for
Comparing how the market prices income across nearby buildings, tracking whether pricing for a submarket is tightening or loosening, and framing the first pass of a valuation conversation.
Where it stops helping
Physical condition, management quality, lease structure, tenant concentration, and capital needs. Those get checked directly, from inspection notes and the rent roll, not inferred from a ratio.
Cash flow under higher financing costs
Higher-for-longer rates changed the arithmetic for a lot of owners. Debt that was cheap to refinance is not cheap anymore, and a property that cash-flowed comfortably under an older loan can go tight when it resets. This is where debt-side players like Starwood Property Trust become worth watching, because their activity reflects how constrained the capital markets actually are.
Our approach is to stress the property before the lender does. We model the new payment at a realistic rate, check debt coverage, and identify what has to change if the numbers do not work. Sometimes the answer is an expense reduction. Sometimes it is a rent adjustment. Occasionally it is a sale.
What the stress test covers
- Payment at reset, at a rate the market is actually quoting rather than the one in the original plan.
- Debt coverage after the new payment, including the escrows that come with the loan.
- Cash remaining after debt service, taxes, insurance, and a reserve for capital work.
- The gap, if one opens, and the specific levers that could close it.
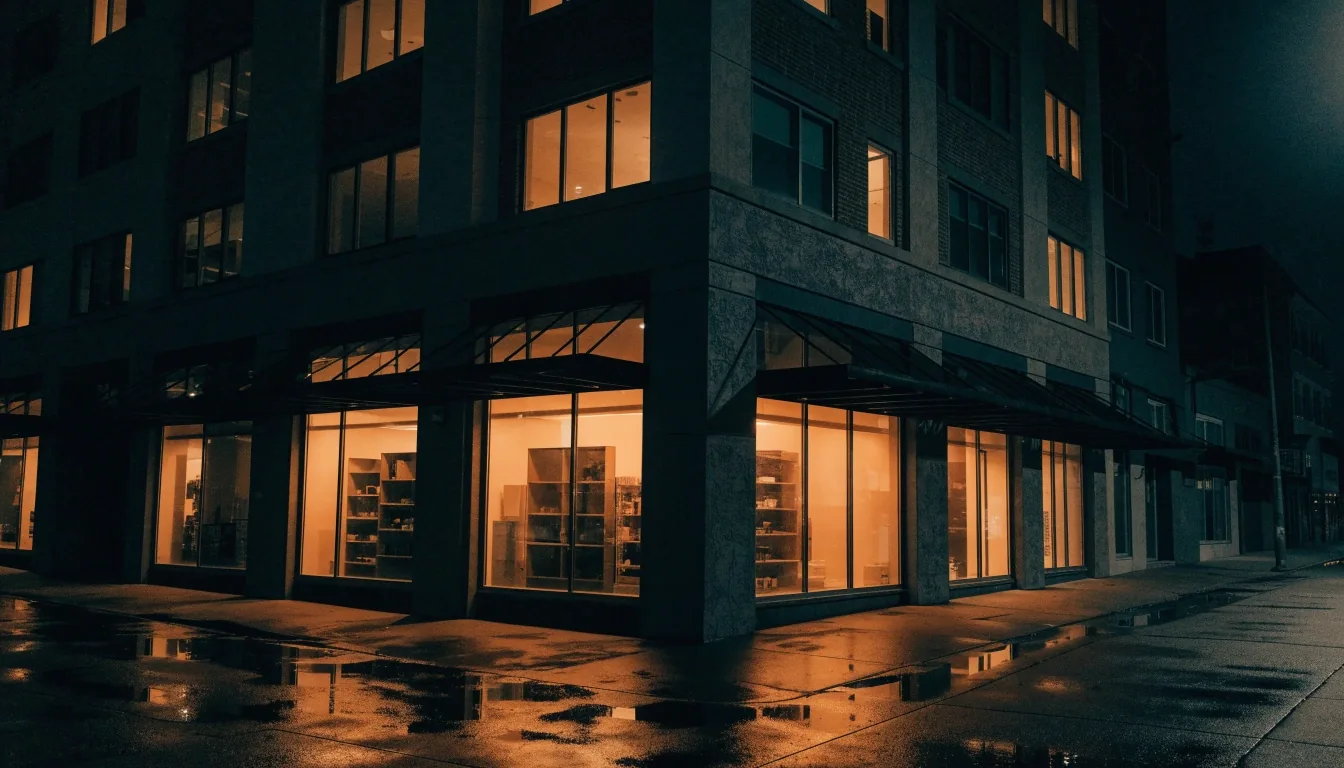
Mixed-use frontage and residential floors above — income from two different sources, and two different sets of risks
Repositioning and value-add, scoped honestly
Value-add means improving a property's income or condition to change its position in the market. It can mean unit renovations, common area work, a management overhaul, or a change in tenant mix. The scope should follow the return, not the other way around.
We cost the work, estimate the income effect, and show what has to be true for it to pay back. If a renovation only works at rents the submarket will not support, that is a finding, not a plan. Owners who want a green light regardless of the numbers are better served elsewhere.
Cost side
Scope of work priced against local contractor rates
Return side
Income effect tested at achievable rents, not aspirational ones
Timing
Hold period and exit assumption stated openly
Downside
What happens if the plan only half works
Apartment demand and the ownership question
Multifamily has stayed resilient partly because homeownership got more expensive. AvalonBay Communities builds its outlook around that affordability pressure, and Equity Residential has been adapting as rent growth normalizes in major metros. Both are useful reads on where professionally managed rental housing is heading.
That does not mean every apartment building performs the same. A 1960s Valley fourplex and a coastal institutional property face different tenants, different competition, and different rent ceilings. The demand story is real; the local application still has to be checked property by property.
Retail and commercial positions
Retail has adapted rather than disappeared. Simon Property Group, the largest U.S. mall owner, focuses on high-performing centers and premium destinations, which tells you where the operating quality concentrates. Weaker centers do not get managed into strength by wishful thinking.
Office is a service business now. JLL, Cushman & Wakefield, and Avison Young all work the repositioning problem through tenant services, building operations, and workplace strategy rather than rent cuts alone. For an owner holding office space, that reframes the question from what rent a tenant will pay to why that tenant would stay.
Self-storage as a different model
Public Storage, the largest self-storage REIT in the country, shows how operationally simple assets work. Revenue depends on occupancy, convenience, and local demographics rather than on tenant improvements or long lease negotiations. Household transitions and space-constrained living drive demand.
For an owner considering storage, the analysis shifts. There is less tenant management and more emphasis on location, visibility, and rate management over time.
Debt, refinancing, and timing
Every property with a loan has a maturity date, and that date is a planning deadline whether the owner treats it as one or not. Starting the refinancing conversation twelve months out gives options: fix the property's numbers, pay down principal, or sell into a stronger market.
Starting it sixty days out gives you whatever the lender offers. The difference between those two situations is mostly calendar discipline, and it costs nothing to get right.
Twelve months out
Options open
Refinance, pay down, or sell
Six months out
Options narrowing
Numbers must already be in shape
Sixty days out
Whatever the lender offers
Little room left to move
Tell us your maturity date early and we will work backward from it: what has to be true at application, which documents the lender will ask for, and which items on the property still need attention before anyone runs the numbers.
Questions owners bring to an asset review
What do you need from me to start?
A rent roll, a trailing twelve-month operating statement, your loan terms, and any inspection or capital plan you already have. If something is missing, we say so rather than filling the gap with an assumption.
Can you work with a property that is already in a loan covenant issue?
Yes, and the first job is getting the real numbers in front of the lender. Lenders respond to a documented plan for coverage far better than to a request for patience with no figures attached.
Do you handle the property operations as well as the analysis?
We do. Investment decisions and day-to-day management are the same conversation here, which matters when a rent adjustment or a repair schedule has to line up with the debt calendar. See Property Management Services for what the operating side covers.
How do you handle a building where the plan does not work?
We show what has to change for it to work and what the downside looks like if it does not. Sometimes the honest answer is to hold and pay down debt, sometimes it is to sell. A review is not a commitment to a transaction.
Which property types do you look at?
Multifamily, mixed-use, retail, office, and self-storage across Los Angeles County. Property Types We Manage covers how the analysis changes between them.
Bring us the property and the maturity date
An asset review starts with the numbers you already have. Tell us where the property sits, what the loan looks like, and what decision is coming up, and we will tell you what we would check first. No obligation to move forward, and no pressure to make a change the figures do not support.
KILTY, LLC — 4239 Stern Ave, Sherman Oaks, CA 91423. Monday to Friday, 9:00 AM to 6:00 PM.
Where to go next
If you are weighing a refinancing, a renovation, or a sale, the useful next step is a conversation with your actual numbers on the table. These pages cover the rest of how KILTY, LLC works with owners in Sherman Oaks and across Los Angeles County.
- About KILTY, LLC The firm, its standards, and the market it works in
- Property Management Services Day-to-day operations behind the income figures
- Property Types We Manage How multifamily, retail, office, and storage differ
- Owner Resources & Market Notes Operating conditions and market reads for owners
- Contact KILTY, LLC Request an asset review or discuss a timeline